

Collateral is the property itself, and in a hard money loan, it's what actually gets you approved. Unlike a traditional mortgage that leans on your income and credit history, hard money lending is asset-based: the value of the property backing the loan determines how much you can borrow, not your W-2 or tax returns.
If you're weighing a hard money loan for an investment property and want to understand how much the collateral actually matters, this guide breaks down how lenders evaluate a property, how its value shapes your loan amount, and what role condition and renovation potential play in the equation.
What Is Collateral in a Hard Money Real Estate Loan?
In a hard money loan, collateral is the real estate securing the debt, the property you're purchasing or refinancing. Hard money loans are asset-based, meaning they're centered on the value of the property involved in the deal rather than the borrower's ability to repay through income documentation.
That distinction is what makes hard money financing move faster than a bank loan. Because the property itself is what a lender is underwriting, there's no need to chase W-2s, pay stubs, or years of tax returns before a deal can close. The collateral does most of the qualifying work, which is exactly the model most private lenders for real estate USA rely on when evaluating investment properties.
How Do Hard Money Lenders Evaluate Property as Collateral?
Evaluating collateral starts with the property's current value and what it's realistically worth once any planned work is complete. This applies across deal types, whether you're financing a distressed single-family flip, a rental property, a construction project, or a multifamily building.
The evaluation typically follows the appraisal. Once an appraisal report comes in, a lender can move quickly toward underwriting, since the property's value, not a personal financial history, is the primary qualifier. That's also why the type of property and the scope of the project both factor into how a lender assesses collateral: a rental property being evaluated on its income potential looks different on paper than a distressed flip being evaluated on its after-repair value.
Hard money lenders for real estate generally follow this same asset-first approach regardless of the specific property type, which is what separates this kind of financing from a conventional bank underwriting process.
How Does Property Value Affect the Loan Amount?
Property value sets the ceiling on what you can borrow, and the specific way it's calculated depends on the loan type. Across InstaLend's five loan products, each one ties the loan amount to a different measure of value:
Fix and flip loans fund up to 90% of the purchase price plus 100% of rehab costs, so the collateral value includes both the property's current worth and its projected after-repair value.
Single family rental loans go up to 80% loan-to-value, qualified on the property's rental income rather than a renovation plan.
New construction loans release funding on a draw schedule as the project progresses, since the collateral value builds in stages as construction advances.
Multifamily bridge loans fund up to 80% loan-to-cost for properties being acquired, renovated, or repositioned.
Multifamily term loans are qualified on the property's Net Operating Income rather than a fixed LTV, reflecting the fact that these are stabilized, income-producing assets.
In every case, the loan amount traces back to what the collateral is worth, current value, projected value, or income it generates, rather than what your personal finances can support. This is the same structure most real estate investment lenders use to size a loan, whether the deal is a single flip or a multi-unit acquisition.
What Role Does LTV Play in Hard Money Financing?
Loan-to-value (and its close relative, loan-to-cost) is the ratio between how much you're borrowing and what the collateral is worth. It's the mechanism that translates a property's evaluated value into an actual loan amount, and it varies by product because different projects carry different levels of risk.
A fix and flip loan, for instance, can fund up to 90% of purchase price plus all of the rehab costs, reflecting the fact that the lender is underwriting both today's value and tomorrow's projected value once renovations are complete. A single family rental loan tops out at 80% LTV, since it's a longer-term hold qualified on rental income rather than a short renovation timeline. A multifamily bridge loan uses loan-to-cost up to 80%, covering acquisition and renovation budget together for a property still in transition.
The common thread: the stronger and more predictable the collateral's value, the more a lender can extend against it. LTV is simply how that relationship gets expressed as a number.
Can Property Condition and Renovation Potential Affect Collateral Value?
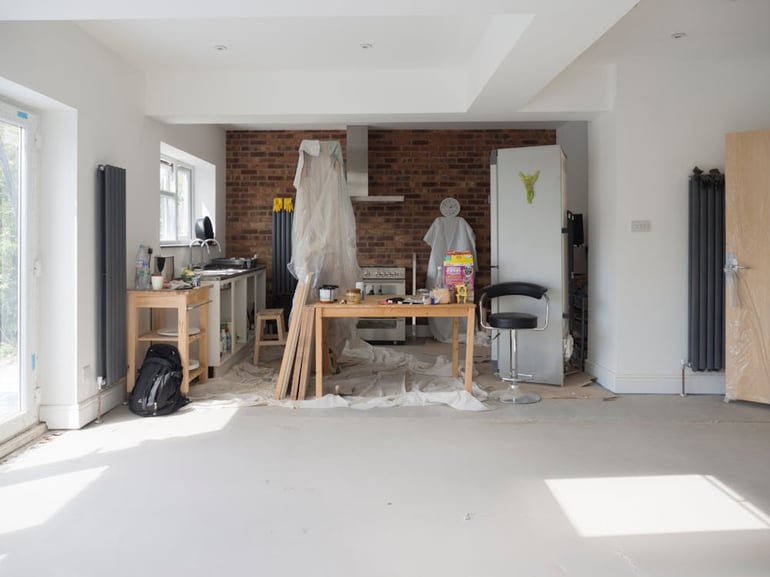
Yes, and this is one of the biggest differences between hard money lending and conventional financing. A distressed property that a bank would reject outright can still serve as strong collateral for a hard money loan, because the lender is evaluating what the property can become, not just its condition today.
This shows up directly in how fix and flip loans are structured: financing covers both the purchase price and 100% of rehab costs, which means the renovation plan itself becomes part of the collateral calculation. The same logic applies to construction loans, where funding releases in phases as the project, and therefore the collateral's value, builds toward completion.
Property condition doesn't disqualify a deal in hard money lending the way it often does with a bank. It shapes how the loan is structured, but it rarely closes the door entirely, which is exactly why distressed and undervalued properties are common candidates for this type of financing, and why so many real estate investor loans USA are structured around potential value rather than current condition.
Hard Money Real Estate Financing From InstaLend
We built our hard money lending around the property, not your personal financial history. Every loan we offer, fix and flip, single family rental, new construction, multifamily bridge, and multifamily term, is asset-based, so no W-2s, pay stubs, or tax returns stand between you and a funding decision.
We give you a loan commitment the same day you submit your deal details, and we typically close within 7 to 14 business days of receiving the appraisal report. There are no upfront fees to begin processing your loan, and we lend across 46 states, so you can put strong collateral to work wherever the deal is, not just where your bank happens to have a branch. It's part of why investors searching for private lenders for real estate investors nationwide consistently land on asset-based models like ours.
If you're not sure how a specific property's value or condition would translate into a loan amount, our team can walk through the numbers with you before you apply.
FAQs
What is collateral in a hard money loan?
The real estate securing the loan. Hard money lending is asset-based, so the property's value, not the borrower's income or credit history, is the primary factor in approval.
How do lenders evaluate a property as collateral?
Based on its current value and, depending on the loan type, its projected after-repair value, rental income, or Net Operating Income, typically confirmed through an appraisal.
Does property condition affect whether I can get a hard money loan?
Not in the way it does with a bank. Distressed or undervalued properties commonly qualify for hard money financing because the lender evaluates the property's potential, not just its current condition.
What is LTV in hard money lending?
Loan-to-value (or loan-to-cost) is the ratio between your loan amount and the collateral's value. It varies by loan type, from up to 90% on fix and flip purchase price to up to 80% on rental and multifamily bridge loans.
Do I need income documentation if my collateral is strong?
No. All hard money loans through InstaLend are asset-based, approval depends on the property's value and income potential, not personal W-2s, tax returns, or employment history.