

Most 1–4 unit single-family residential properties qualify for fix and flip financing, including distressed, undervalued, and off-market properties that need anywhere from cosmetic touch-ups to a full gut renovation. What matters most to a lender isn't the property's current condition, it's the deal itself: purchase price, renovation scope, and projected after-repair value (ARV).
If you're evaluating a potential flip and wondering whether it's financeable, this guide walks through exactly what qualifies, how property condition factors into approval, and what you should check before you submit an application.
What Properties Qualify for Fix and Flip Financing?
Fix and flip financing is built around one core property type: 1–4 unit single-family residential real estate. That covers standalone houses, duplexes, triplexes, and fourplexes, the bread-and-butter inventory for most investors.
Beyond property type, here's what typically qualifies:
- 1–4 unit single-family residential properties, the standard eligible asset class for this loan type
- Distressed properties, homes with deferred maintenance, code violations, or structural issues that scare off retail buyers
- Undervalued properties, priced below market due to condition, seller motivation, or limited exposure
- Off-market properties, acquired through wholesalers, direct mail, or auction rather than the MLS
- Properties requiring cosmetic renovations, paint, flooring, fixtures, and landscaping
- Properties requiring major renovations, full kitchen and bath overhauls, roofing, plumbing, or electrical work
Because asset-based lending evaluates the deal rather than your personal finances, a property doesn't need to be move-in ready to qualify. In fact, distressed and undervalued properties are often exactly what this financing model is designed for.
Can You Finance a Distressed or Foreclosure Property?
Yes, and this is one of the biggest differences between hard money and conventional financing.
-
Why distressed properties may not qualify for conventional financing
Banks and conventional lenders underwrite based on the property's current condition and the borrower's income documentation. A home with a damaged roof, outdated electrical, or missing appliances often fails a conventional appraisal outright, regardless of how strong the surrounding market is.
-
How asset-based financing approaches these properties
Asset-based lenders look past current condition to the property's potential. Instead of asking "would a family move in tomorrow?" the underwriting question becomes "what will this property be worth once the renovation plan is executed?" That shift is what makes distressed inventory financeable in the first place.
-
Foreclosures and short sales as potential fix-and-flip opportunities
Foreclosure and short sale properties are frequently priced well below market value precisely because their condition or title situation disqualifies them from traditional mortgages. For investors willing to take on the renovation work, these deals can offer some of the strongest margins available, provided the numbers on purchase price, rehab cost, and ARV pencil out.
How Does Property Condition Affect Fix and Flip Financing?
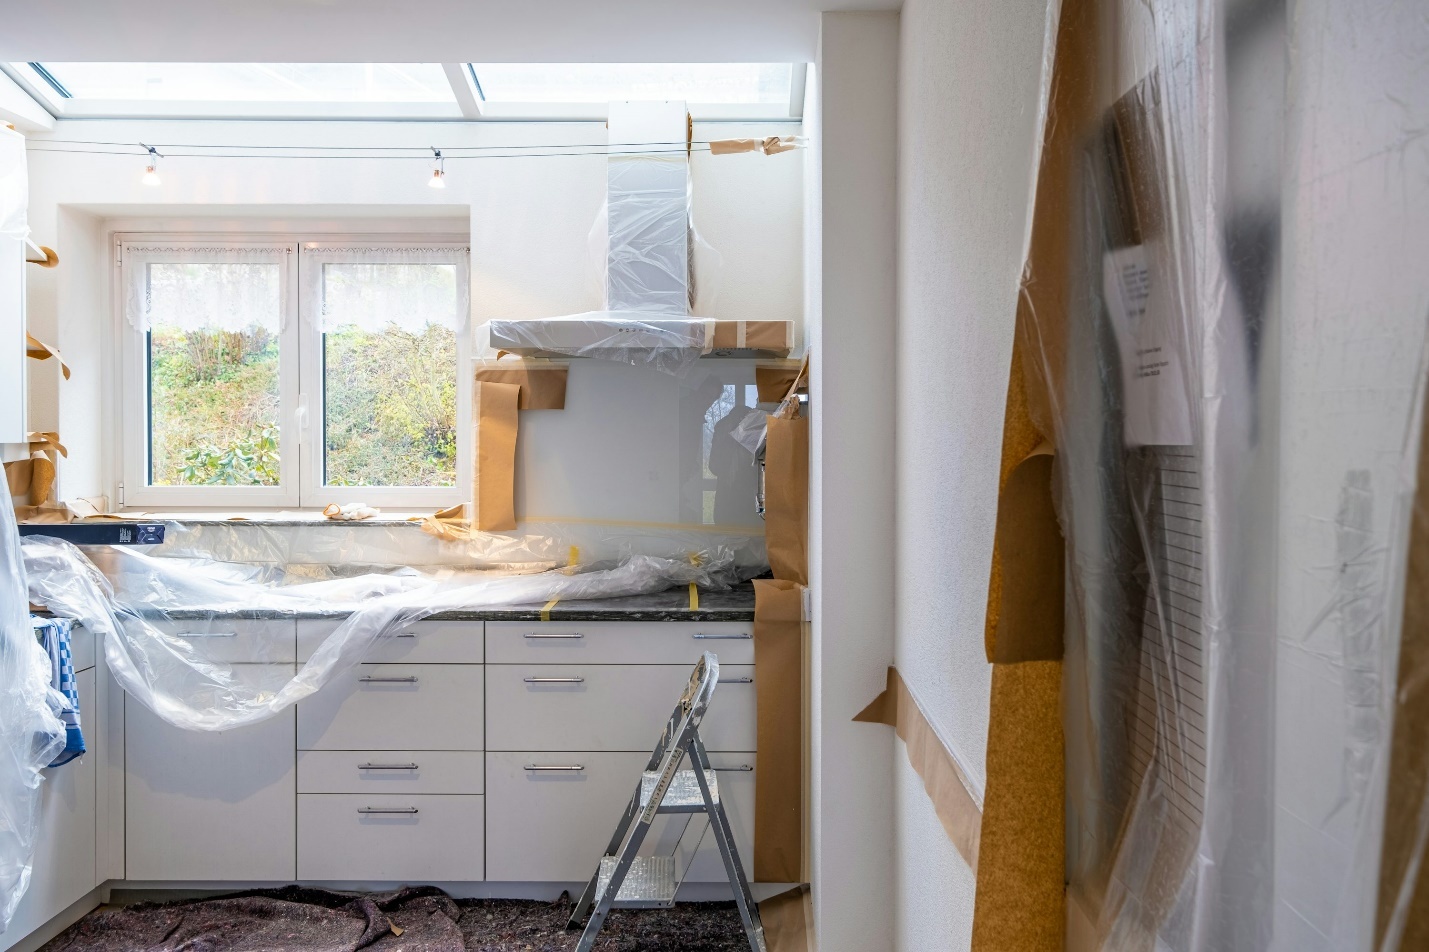
Property condition doesn't determine whether you qualify so much as it shapes how the deal is structured, loan amount, draw schedule, and timeline all flow from the renovation scope.
-
Cosmetic repairs
Surface-level work like paint, flooring, and fixture replacement is the lowest-risk renovation category. These projects typically move fastest, since there's little uncertainty about scope once work begins.
-
Kitchen and bathroom renovations
Kitchens and bathrooms tend to drive the largest share of ARV lift per dollar spent. They're also where renovation budgets most often run over, so accurate cost estimates here matter more than almost anywhere else in the project.
-
Curb appeal improvements
Landscaping, exterior paint, and entryway updates are relatively inexpensive but heavily influence a buyer's first impression, and, by extension, how quickly the property sells once it's listed.
-
Major renovations such as roofing, plumbing and electrical work
Structural and systems work carries more risk and more cost, but it's also often what unlocks the biggest spread between purchase price and ARV. Full gut renovations fall into this category and require more capital upfront, along with a more detailed scope of work.
-
Current condition vs. projected condition
The single biggest mindset shift for new investors is understanding that a lender isn't just financing what a property is today, they're financing what it will become. That's why a clear, itemized renovation plan carries real weight in how your deal gets evaluated.
How Do Purchase Price, Renovation Costs, and ARV Affect the Loan?
These three numbers form the backbone of every fix and flip deal, and they're interdependent, change one, and the others shift too.
-
Purchase price - What you pay upfront sets the floor for your total project cost and directly affects your margin at exit. Many experienced investors use the 70% rule as a starting filter: purchase price should generally sit at or below 70% of ARV, minus renovation costs.
-
Renovation budget - Your renovation budget needs to reflect real contractor bids, not rough guesses. Underestimating rehab costs is one of the most common reasons flips underperform their projected profit.
-
After-repair value (ARV) - ARV is the estimated market value of the property once renovations are complete, based on comparable recent sales. It's the anchor figure lenders use to determine how much financing a deal can support.
-
Loan-to-cost (LTC) - LTC measures the loan amount against total project cost (purchase plus rehab), rather than against the property's current or future value alone. A higher LTC means more leverage, and less of your own capital tied up in the deal.
-
Why the lender evaluates the overall deal - No single number tells the whole story. A low purchase price with a bloated renovation budget can be just as risky as an aggressive ARV estimate with minimal rehab planned. That's why fix and flip lenders look at the full picture, price, scope, and projected value together, rather than any one input in isolation.
What Should You Check Before Financing a Fix and Flip Property?
Before you apply for fix and flip loans, run through this checklist to make sure your deal is ready to submit:
- Property type — Confirm it's a 1–4 unit residential property, the standard eligible asset class.
- Purchase price — Verify it against recent comparable sales and your target LTC.
- Renovation scope — Document exactly what work is planned, room by room.
- Estimated renovation costs — Get real contractor quotes, not ballpark estimates.
- Projected ARV — Pull comps from properties that have actually sold, not just listed.
- Exit strategy — Decide upfront whether you're selling or refinancing into a long-term rental loan, since that shapes your timeline and loan term.
Having these six items organized before you apply speeds up underwriting significantly, since it's exactly the information a lender needs to evaluate your deal.
Fix and Flip Financing From InstaLend
We built InstaLend's fix and flip loan around the way asset-based lending is supposed to work: the deal qualifies, not your pay stub. We finance up to 95% of total project cost, purchase and rehab combined, with no income verification required, and most loans close in 10–14 days.
Eligible properties are 1–4 unit single-family residential, loan amounts range from $50,000 to $5M+, and rehab costs are disbursed through a draw schedule as your renovation progresses. Whether you're taking on a cosmetic refresh or a full gut renovation, our team evaluates your deal based on ARV, purchase price, and renovation plan, not your tax returns.
We lend in 46 states nationwide, and if your plan is to hold the property as a rental once it's stabilized, you can refinance directly into our long-term single-family rental loan under one roof.
Fix and Flip Loan FAQs
What types of properties qualify for fix and flip financing?
1–4 unit single-family residential properties qualify, including distressed, undervalued, off-market, and foreclosure properties needing cosmetic or major renovation.
Can I get financing for a foreclosure or short sale property?
Yes. Asset-based lenders evaluate the property's after-repair value rather than its current condition, which makes foreclosures and short sales financeable even when they wouldn't qualify for a conventional mortgage.
Does property condition affect how much I can borrow?
It affects how the loan is structured, renovation scope influences your draw schedule and total project cost, but it doesn't disqualify a property on its own.
What is ARV and why does it matter for approval?
ARV, or after-repair value, is the estimated market value once renovations are complete. Lenders use it alongside purchase price and renovation budget to determine loan amount and structure.
What should I prepare before applying?
Have your property type, purchase price, renovation scope and cost estimates, projected ARV, and exit strategy ready, this is the core information underwriting needs to evaluate your deal.