

Yes, you can get a construction loan for a spec home. A spec home, short for "speculative home," is a house built without a committed buyer lined up in advance, the builder finances construction on the expectation that it will sell once finished, rather than building to a specific buyer's order. Construction loans are one of the main ways builders and investors fund that gap between breaking ground and closing a sale.
Because there's no buyer contract backing the project, lenders evaluating a spec home focus heavily on the builder's plan, the budget, and what the finished property is likely worth. Here's how spec home financing actually works.
What Is a Spec Home Construction Loan?
A construction loan is short-term financing that funds the ground-up building of a property. Instead of handing over the full loan amount upfront, the lender releases funds in stages, or "draws," as the build hits milestones like foundation, framing, and finish work.
A spec home construction loan applies that same structure to a speculative build: no signed buyer, no lease in place, just a property the builder plans to sell at or after completion. Most residential construction loans work this way regardless of whether a buyer is already lined up. Because repayment depends on a future sale rather than an existing income stream, these loans are typically asset-based, the lender is financing the project and its projected value, not the builder's personal paycheck.
How Do Construction Loans for Spec Homes Work?
Most real estate construction loans, spec or otherwise, follow a similar pattern:
- Draw-based funding. Money is released as work is completed and verified, not all at once.
- Interest-only payments. You typically pay interest only on the amount you've drawn, not the full approved loan.
- Loan-to-cost (LTC) basis. The lender caps financing as a percentage of total project cost, land plus construction, rather than a flat dollar figure.
- Short loan term. Construction financing is usually structured around the build timeline, often 12 months or so, not a 30-year amortization.
Terms vary by lender and project, so treat any specific rate, LTC percentage, or timeline you see elsewhere as an example rather than a guarantee for your deal.
What Do Lenders Look for When Financing a Spec Home?
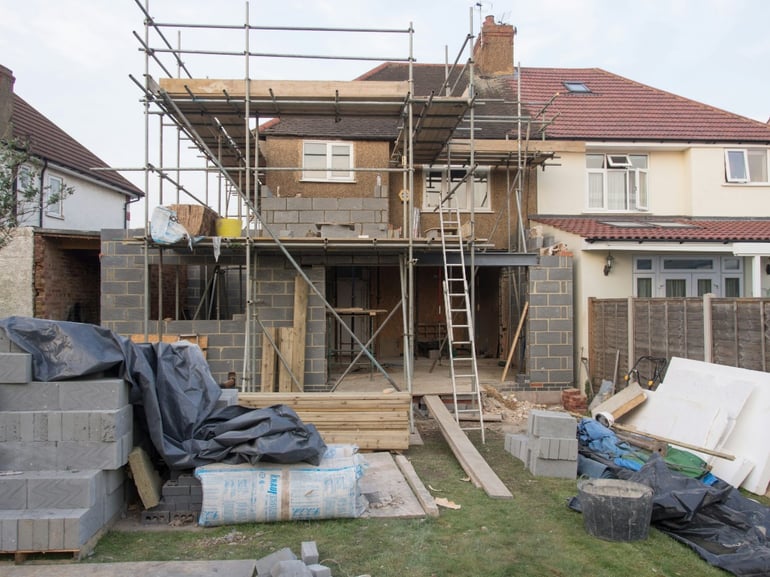
Because a spec home doesn't have a buyer or tenant lined up, lenders lean more heavily on the project itself and the builder behind it:
- Builder experience, a track record of completed builds, or a licensed general contractor on the project.
- Construction plans and budget, detailed scope of work and realistic cost estimates.
- Land value and purchase price, what the lot costs relative to the finished project.
- Projected completed value, what the home is expected to sell for once built.
- Loan-to-cost ratio, how much of the total project the loan is expected to cover.
- Market and exit plan, how quickly comparable homes in the area typically sell.
These are general considerations, and no single factor guarantees approval, every lender weighs the full picture differently. InstaLend, specifically, requires borrowers to be a licensed general contractor or to have demonstrated prior construction experience, and approval is based on the project's loan-to-cost ratio rather than personal income.
What Costs Can a Spec Home Construction Loan Cover?
Construction loan financing commonly covers costs tied directly to the build, such as:
- Land or lot purchase
- Site preparation and permitting
- Foundation, framing, and structural work
- Mechanical, electrical, and plumbing systems
- Finish work and final inspections
Coverage varies by lender and loan structure, some finance land and construction together, others only the build itself. On InstaLend's new construction loan specifically, financing can cover up to 90% of total project cost, combining acquisition and build costs, released through milestone-based draws as work is completed.
How Do You Repay a Construction Loan for a Spec Home?
Spec home construction loans are typically repaid one of two ways once the build wraps up:
- Sale of the property. The most common path for a true spec build, you sell the finished home and use the proceeds to pay off the loan.
- Refinance into long-term financing. If plans change and you decide to hold the property instead, you can refinance into a longer-term mortgage or rental loan.
Because the loan term is short, having a realistic sale timeline (or a refinance plan as a backup) matters before construction even starts. On InstaLend's construction loan, there's no prepayment penalty, so paying it off early through a sale doesn't carry an added cost, and the stated exit options are selling the property or refinancing into a long-term mortgage.
Spec Home Construction Loans From InstaLend
Spec home building is one of the project types our new construction loan is built for: you build in a market where finished homes are in demand, then sell at completion, with milestone draws keeping your carrying costs down while the project is underway.
Our construction loan financing runs from $50,000 to $5 million or more, covering up to 90% of total project cost. The loan term is 12 months, with extensions available, and interest is charged only on the amount you've drawn. We don't require income verification, no W-2s or tax returns, and pre-approval typically takes 24–48 hours, so you can move on land and contractor agreements with more confidence. Borrowers need to be a licensed general contractor or have prior construction experience, and there's no prepayment penalty if your project sells ahead of schedule.
If you're planning a spec build, you can apply for a construction loan or request pre-approval before you finalize your land purchase.
FAQs
What is a spec home?
A spec home is a house built without a committed buyer in place, on the expectation that it will sell once finished.
Can you get financing to build a spec home?
Yes. New construction loans, including InstaLend's, are commonly used to finance spec home builds.
How is a construction loan for a spec home repaid?
Typically through the sale of the finished property, or by refinancing into long-term financing if you decide to hold it instead.
Do I need construction experience to get approved?
Requirements vary by lender. InstaLend requires a licensed general contractor or demonstrated prior construction experience.