

Pennsylvania’s construction market is heating up fast, with home prices going up by 7.5% in February 2025. With this rise in demand, builders can’t afford delays in financing.
However, traditional banks often move too slowly. That’s why developers across the state are turning to new construction loans from flexible real estate lenders who understand the urgency of breaking ground. If you’re ready to build, here’s what you need to know.
What is a New Construction Loan?
A new construction loan is a short-term financing option designed to cover the cost of building a new home, residential development, or commercial project. Unlike a traditional mortgage that provides one lump sum of funds, construction loans are disbursed in stages based on project milestones.
The primary goal of a construction loan is to fund the costs of construction as they occur. These loans provide cash to builders and developers as they move through the phases of building, from site preparation and foundation work to framing and final touches. Once construction is completed, the loan can either be converted into a permanent mortgage or paid off in full.
Key Features of New Construction Loans:
- Draw Schedule: One of the defining features of construction loans is the draw schedule. Funds are released to the borrower in increments as specific milestones are met during construction. For example, funds may be disbursed after the foundation is poured, after framing is completed, and so on.
- Loan Term: Construction loans are short-term, typically ranging from 6 months to 3 years. Once construction is completed, the loan is either paid off or converted into a permanent mortgage.
- Down Payment: Just like with traditional loans, construction loans require a down payment. The amount can range from 20% to 25% of the total project cost, depending on the lender’s requirements.
How New Construction Loans Work in Pennsylvania
When you apply for a new construction loan in Pennsylvania, the lender will evaluate several key factors to determine whether you qualify for funding. This includes reviewing your financial history, the construction plans, and the projected value of the property upon completion.
The process typically unfolds in the following steps:
- Application and Approval: To apply for a construction loan, you’ll need to provide detailed construction plans, a budget, and an estimated timeline. The lender will assess your creditworthiness and the financial viability of the project.
- Loan Disbursement: Once approved, the funds are released based on a pre-established draw schedule. These disbursements are typically made to the contractor or builder handling the work.
- Construction Period: During construction, you’ll only be required to make interest payments on the funds that have been disbursed. The loan’s principal will be due once the construction is completed.
- Conversion or Payoff: Upon completion, you can either convert the construction loan into a traditional mortgage or pay off the remaining balance in full.
Understanding the Main Construction Phases
Planning and Design: Work with architects and designers to create detailed plans for your home. This includes selecting materials, finalizing layouts, and obtaining necessary permits.
Site Preparation: This involves clearing the land, excavating, and laying the foundation. It is essential to coordinate with contractors to ensure that this phase progresses smoothly.
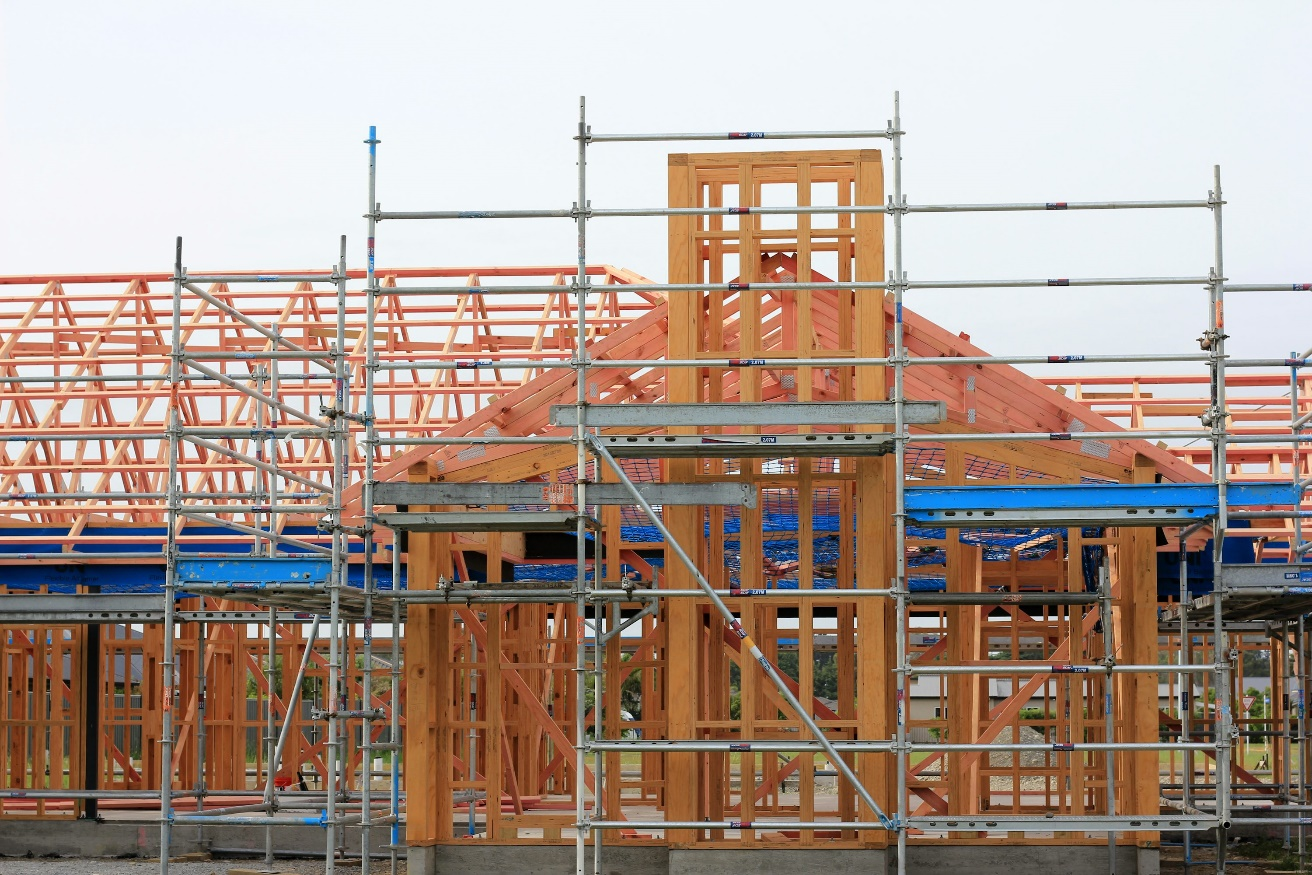
Construction: During this phase, the structure of the home is built, including framing, roofing, and installing systems such as plumbing and electrical. Regular site visits and communication with your builder are vital to address any issues promptly.
Finishing Touches: The final phase involves interior and exterior finishing, including painting, flooring, and landscaping. Ensuring that all details are completed to your satisfaction is key to achieving your dream home.
Staying Involved Throughout Construction
Stay Involved: Be actively involved in the construction process. Regular updates and site visits help ensure your vision is executed correctly.
Communicate Clearly: Maintain open lines of communication with your builder and contractors. Clear communication helps resolve issues quickly and keeps the project on track.
Quality Control: Pay attention to the quality of work at every stage. Ensure that the materials used and the workmanship meet your expectations.
Why New Construction Loans Are Essential in Pennsylvania’s
In Pennsylvania, developers and builders face specific challenges when it comes to securing financing for new construction projects. Long permitting processes, rising material costs, and tight timelines often make traditional financing methods less viable.
New construction loans provide the flexibility and speed needed to overcome these obstacles and keep projects moving forward.
Managing Your Construction Budget
Create a Detailed Budget: Break down all expenses, including materials, labor, permits, and contingency funds. Having a clear understanding of costs helps prevent surprises.
Monitor Spending: Regularly compare actual expenses against your budget to identify any deviations early. This allows you to make adjustments and avoid overspending.
Set Aside Contingency Funds: Allocate a portion of your budget for unexpected expenses. Construction projects often encounter unforeseen challenges, and having contingency funds ensures that these do not derail your project.

Some of the key advantages of using new construction loans in Pennsylvania include:
- Faster Access to Funds: One of the most significant advantages of new construction loansis their speed. Traditional financing can take weeks or even months to approve, whereas construction loans are designed to expedite the process, allowing projects to begin without unnecessary delays.
- Flexibility in Loan Structure: Construction loans can be customized to fit the specific needs of your project. This flexibility can be crucial when dealing with unforeseen changes or challenges during construction.
- Access to Funds as You Need Them: Unlike a standard loan, construction loans provide funds as the project progresses, ensuring that you always have access to the necessary capital at each stage of construction.
Hard Money Loans: A Viable Option for Pennsylvania’s
In some cases, hard money loans in Pennsylvania may be a viable alternative for securing construction funding. These loans are provided by private lenders, and the primary requirement for securing a hard money loan is the value of the property being used as collateral.
While they typically come with higher interest rates and fees, hard money loans offer several advantages, particularly for projects that require fast approval and disbursement.

Advantages of Hard Money Loans for Construction Projects:
- Speed: New construction loansby hard money lenders can be approved and funded much faster than traditional construction loans, making them ideal for projects that need quick financing.
- Fewer Requirements: Hard money lendersare more likely to base their approval decisions on the property’s value rather than your credit score or financial history.
- Flexibility: Hard money loansoffer more flexibility in terms of repayment schedules, allowing for customized repayment plans that align with your project’s needs.
- No Prepayment Penalties: Many hard money loanscome without prepayment penalties, which can be beneficial if you plan to pay off the loan early or convert it into a longer-term mortgage once the construction is completed.
InstaLend Offers Flexible Hard Money Loans For Pennsylvania’s Construction Market
Ready to break ground in Pennsylvania’s construction market? InstaLend makes funding your residential or commercial project fast, flexible, and simple. With quick approvals and no prepayment penalties, our new construction loans in Pennsylvania are designed to keep your build moving without delays.
Whether you're starting from scratch or expanding your portfolio, we help you stay on schedule and within budget. Work with our hard money lenders because we understand what builders need. Apply now with InstaLend and get one step closer to completing your next successful project.