

A hard money construction loan is short-term, asset-based financing that pays for a ground-up build in stages as the work gets done. Instead of judging you by your paycheck, the lender looks at the project: what it costs, what it will be worth, and who is building it.
If you build or invest in small residential properties, this structure can open doors that bank financing often keeps closed. This guide explains how these loans work, which properties qualify, what lenders expect, and how to get ready before you apply.
What Are Hard Money Construction Loans for 1–4 Unit Properties?
They’re short-term loans from private lenders that fund new builds on residential properties with one to four units. The property and the project secure the loan, so approval depends on the deal and your building experience, not your tax returns.
The “hard money” label points to how the lender decides. A traditional bank asks whether you can repay based on your personal income. A hard money lender focuses on the asset, meaning the value of the property involved in the deal. That’s why investors with complicated income, or no traditional employment, can still qualify.
Construction financing also pays out differently from a regular mortgage. You don’t receive the full amount at closing. The lender releases money in stages, called draws, as milestones like the foundation, framing, mechanical systems, and finish work are completed. You pay interest only on the funds you’ve actually drawn, which keeps your carrying costs lower in the early months of a build.
The “1–4 unit” part simply describes the building type. It covers a single-family home up to a small building with four units.
Which Investment Properties Qualify for Construction Financing?
Ground-up residential projects of one to four units are the usual fit. Lenders in this space generally want a new structure being built from scratch on a lot you own or are about to buy.
Many residential construction loans that serve investors support several common strategies:
- Spec homes. You build without a buyer in place, then sell the finished home.
- Build-to-rent. You build to hold the property as a long-term rental.
- Custom homes for clients. A licensed builder constructs a pre-sold or custom home for an end buyer.
- Infill projects. You build on a vacant or teardown lot in an established neighborhood where land is scarce.
- Teardown and rebuild. You demolish an outdated structure and build new on the same lot.
Investor-focused products usually aren’t meant for people buying a first primary residence. Those buyers tend to be better served by a single-close mortgage that converts after the build.
Location matters too. Lenders don’t lend everywhere, so confirm that your project’s state is covered before you spend time on plans and budgets. We list the areas we serve on our where we lend page.
How Do Hard Money Construction Loans Work?
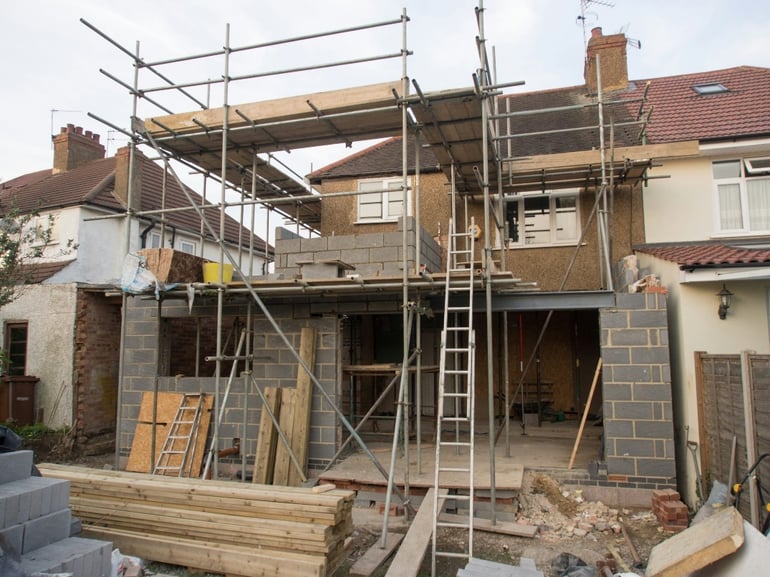
The lender approves the loan based on your project, you close, and then funds flow out in draws after each stage of work is verified. Here’s the sequence from start to finish.
- Before closing. You share your project details, such as the lot location, the scope of the build, the total budget for land and construction, and your builder credentials. The lender reviews the project’s loan-to-cost ratio, which compares the loan amount to the total project cost, along with your experience.
- During the build. When a stage is finished, you submit a Scope of Work (SOW) that shows which line items are complete. You then choose how the work will be verified: a self-inspection, or a third-party inspection ordered through the lender. On the first draw of each new loan, you’ll also confirm your wire details through DocuSign.
- After inspection. Once the lender receives the inspection, funds go out based on your project’s percentage of completion. Wire and inspection fees come out of each draw, so your deposit will be a little smaller than the gross amount.
- At the end. Because these are short-term loans, you finish the build and then exit. Most investors either sell the finished property or refinance into a long-term mortgage. If you want a closer look at how inspections affect draw timing, our guide on self-inspection versus third-party inspection covers it in detail.
What Are the Loan Requirements, Costs, and Terms?
You’ll need builder credentials, a solid plan, and a project that makes financial sense. Costs come mostly from interest on drawn funds and the fees attached to each draw.
What lenders typically ask for:
- Proof that you’re a licensed general contractor, or a record of prior construction experience
- Construction plans, a detailed budget, and a realistic timeline
- A project that passes the loan-to-cost review
Terms to expect. These loans run for a short period, usually about a year, and some lenders allow extensions if the build runs long. Payments are typically interest-only on the amount drawn. Ask about prepayment terms before you sign, since finishing early shouldn’t cost you extra. Our terms include no prepayment penalty.
Costs to budget for. Beyond interest, plan for wire fees and inspection fees on each draw, plus the usual project costs like permits and materials. Add a cushion for surprises, because construction schedules rarely run perfectly.
Before you commit, compare how each type of construction loan financing handles income, closings, and speed.
|
Hard Money Ground-Up |
Construction-to-Permanent |
Bank Stand-Alone |
|
|
Qualified by |
Project costs and builder experience |
Personal income |
Personal income |
|
Income documents |
Not required |
W-2s and tax returns |
W-2s and tax returns |
|
Closings |
One, then sell or refinance |
One, converts to a long-term mortgage |
Two, since you apply again for the permanent loan |
|
Approval pace |
Faster |
Slower |
Slower |
|
Best for |
Builders and investors |
Owner-occupants and long-term holders |
Homebuilders with salaried income |
How to Prepare for Construction Loan Approval
Preparation is mostly about showing a lender that your project is realistic. A clear package also makes your later draw requests easier.
- Gather your builder credentials. Have your contractor license ready, or document your past projects. If you’re new to building, line up a licensed contractor to partner with.
- Write a complete budget. Include the land, the build, and a contingency cushion. Break the construction costs into line items, because you’ll report progress against those same lines when you request draws.
- Set a realistic timeline. Short loan terms leave little room for slow schedules, so build in time for permits and weather.
- Finalize your plans. Lenders want to see what you’re building before they fund it.
- Decide on your exit. Know whether you’ll sell the finished home or refinance it into a long-term loan.
- Seek pre-approval early. Getting pre-approved before you finalize the land purchase or sign with a contractor helps you bid with confidence.
- Choose your inspection style. Think ahead about whether you’ll self-inspect or request a third-party inspection, since you’ll make that choice at every draw.
Keep your records organized as you go. Clean documentation makes each stage smoother and protects your timeline.
How InstaLend Finances New Construction Investment Projects
At InstaLend, we offer new construction loans for investors and builders working on one to four unit residential projects. Our approach is asset-based, so we evaluate the project’s loan-to-cost ratio and your construction experience instead of asking for W-2s or tax returns.
We release funds on a milestone-based draw schedule, and you pay interest only on what you’ve drawn. We also require borrowers to be licensed general contractors or to have prior construction experience. If you’re newer to investing, you can still qualify by partnering with licensed contractors and bringing strong plans and a detailed budget.
Construction isn’t our only hard money product. We also offer fix and flip loans, bridge loans, and land loans, which can help you acquire a parcel before you develop it. If your plan is to build and hold, you can use our construction financing for the build and then move into our rental loan once the property is complete.
Questions Borrowers Often Ask
What is a hard money construction loan?
It’s short-term, asset-based financing for building a new property, released in stages as construction milestones are completed.
Can a first-time investor qualify?
Yes, in many cases. Experience helps, but new investors can partner with licensed contractors and present strong plans and a detailed budget.
Can you get approved before buying the land?
Yes. Pre-approval confirms your eligibility before you finalize the land purchase or sign contractor agreements.